SBP-held reserves rise to $4.6bn on Chinese loan
Met forex reserves held by commercial banks stand at $5.5bn, $941.8m more than SBP
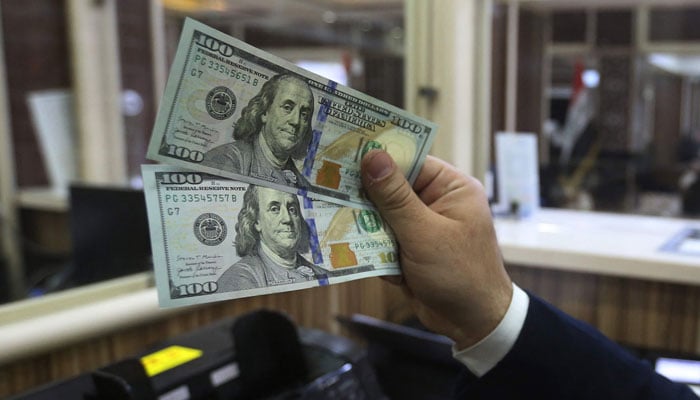
The State Bank of Pakistan (SBP)-held foreign exchange reserves maintained their uptrend for the sixth consecutive session, rising $280 million during the week ended March 17.
Foreign exchange reserves increased by $280 million to $4.6 billion as of the week ended March 17, the central bank said in its weekly bulletin.
A rise was seen after the central bank received $500 million from a Chinese bank last week, consequently, the current position of reserves will provide an import cover of around a month.
The net forex reserves held by commercial banks stand at $5,540.5 million, $941.8 million more than the SBP, bringing the total liquid foreign exchange reserves of the country to $10,139.2 million, the statement mentioned.
On March 17, Pakistan received $500 million —the second disbursement of the $1.3 billion facility — from the Industrial and Commercial Bank of China (ICBC) which boosted the foreign exchange reserves held by the central bank.
Earlier this month, the Chinese lender had approved a rollover of a $1.3 billion loan for Pakistan.
Following the announcement, the Chinese bank deposited $500 million — the first disbursement — on March 4 which helped the foreign exchange reserves surpass the $4 billion mark.
“During the week ended on 17-Mar-2023, SBP received $500 million as [Government of Pakistan] commercial loan disbursement,” the central bank said in the statement, adding that the amount of $4.5 billion was calculated after accounting for external debt repayments.
The Pakistani authorities are running from pillar to post to get 100% confirmation from friendly donor countries and multilateral creditors before moving toward striking a staff-level agreement with the International Monetary Fund (IMF).
The cash-strapped country has faced growing economic challenges, with high inflation, low forex reserves, a widening current account deficit and a depreciating currency.
The coalition government has taken tough measures including increasing taxes and energy prices, and allowing its currency to weaken to restart a $6.5 billion IMF loan package. The funds will offer some relief to a nation still reeling from a dollar shortage that has raised the probability of the economy slipping into a recession ahead of elections this year.
It was the unwritten condition of the IMF that Pakistan must secure the refinancing of commercial loans as well as a rollover on deposits from China during the programme period, which is scheduled to expire in June 2023.


-
 Could Anthropic's IPO beat SpaceX's record?
-
 Tata Steel turns to government for fresh funding as industry crisis deepens: What to know
-
 BOJ rate hike to 31-years high: Economic outlook and broader impact
-
 Gold hits one-week high: Here’s what’s driving the rise
-
 Bank of England sounds inflation alarm as it holds interest rates upto 4%
-
 US jobless claims drop sharply below forecasts: Here’s why
-
 Snap targets enterprise market for specs AR glasses with Salesforce, Nvidia and AWS AI tools
-
 Google agrees biggest carbon-removal deal: What to know
-
 UK FCA eyes tokenized gold to boost London wholesale market liquidity—Here's why it matters
-
Meta launches new subscription with enhanced AI features and premium tools
-
AI stocks crash as top lab CEOs demand emergency technology slowdown amid extinction fears
-
Carney proposes new EU role for Canada: Key details to know