
Alvi signs mini-budget finance bill into law
The Act empowers FBR to slap up to 25 per cent GST on the import of certain luxury items
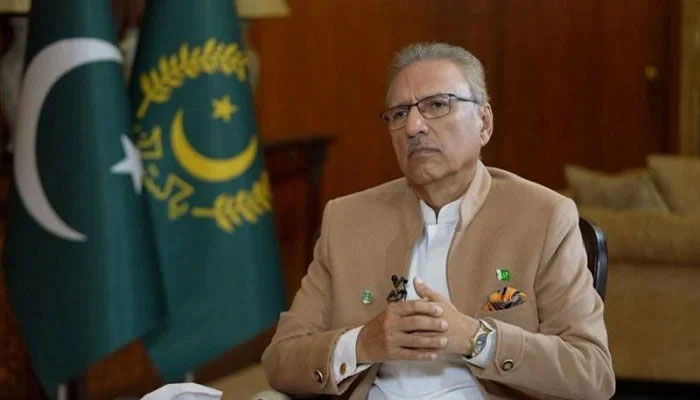
ISLAMABAD: With the assent of President Arif Alvi, the Finance (Supplementary) Bill 2023 has been converted into an Act after which the FBR is empowered to slap up to 25 per cent GST on the import of certain luxury items.
The FBR will now notify the imported items after getting approval from the ECC and the federal cabinet on which higher rates of GST will be imposed.
The FBR now plans to slap a maximum rate of 25 percent GST on those imported luxury items which were earlier banned by the government in the recent past with the objective to reduce the import bill. However, under the WTO rules, the government cannot ban imported items for an indefinite period so it will have to withdraw it and impose a higher rate of Regulatory Duty.
According to the Finance Act 2023 issued by the Federal Board of Revenue (FBR) on Thursday, the federal government may subject to such conditions and restrictions as it may impose, by notification in the official Gazette, declare that the tax on goods specified in the Third Schedule shall be collected and paid at much higher rate or rates on the retail price thereof, as may be specified in the said notification.
Prior to the enactment of this Act, the FBR did not possess powers to impose a 25 percent sales tax through a statutory regulatory order (SRO).
Under the Finance (Supplementary) Act 2023, a person acquiring a capital asset, being shares of a company, shall deduct advance adjustable tax from the gross amount paid as consideration for the shares at the rate of 10 percent of the fair market value of the shares which shall be paid to the commissioner by way of credit to the federal government within 15 days of the payment.
As per the Act, 10 percent FED would be applicable on sugary fruit juices, syrups and squashes, and waters whether or not containing added sugar or artificial sweeteners excluding mineral and aerated waters.


